Amex acceptance varies by service, while Australian law distinguishes payment availability from the legality of offshore real-money casino play.
Specialist reviews have reported American Express deposits as an option at some online casino services discussed in an Australian context. That is a limited statement about payment acceptance, not a recommendation to use those services or an indication that they are lawful to provide in Australia. The Interactive Gambling Act 2001 makes it illegal for operators to offer real-money online casino games to people physically located in Australia. Australian consumer law does not protect players who use offshore casinos.
“Accepts Amex” describes a payment option reported for a particular service; it does not establish a general position across the market. An online casino that takes credit cards may accept one card network and not another, and an Amex option reported at one service cannot be treated as evidence of acceptance elsewhere. The distinction matters because “credit card accepted” is broader than a specific statement about American Express. A general card label does not, on its own, confirm that Amex deposits are available.
The relevant scope is therefore narrow: some specialist reviews have described Amex as a deposit method at certain casino services associated with Australian players. The reports do not establish that every service accepts it, that the option remains available, or that the service is authorised to provide casino games in Australia. Payment acceptance and legal status are separate questions; neither answers the other.
Credit-card availability can vary by casino and payment option, so check the cashier’s current methods before depositing. This list offers a concise reference to the details available for each site.
Roby Casino
Roby Casino is listed as operating under a Curacao eGaming licence held by Roby Games Ltd.
Playfina Casino
Playfina Casino has been licensed by Curacao eGaming through Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
WinSpirit Casino
WinSpirit Casino holds a Curacao eGaming licence, OGL/2024/923/0383, issued through Antillephone N.V. Its minimum deposit is A$30.
Lucky Dreams
Lucky Dreams is listed with a Curacao licence and a minimum deposit of A$20 via POLi.
Bizzo Casino
Bizzo Casino is listed as licensed by the Curacao Gaming Control Board, with TechSolutions Group N.V. identified as the operator.
House of Pokies
House of Pokies lists an international iGaming licence, though the jurisdiction is not named. PayID payouts are stated as taking 1–24 hours; the minimum deposit is A$30, or A$10 with PayID.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence.
SkyCrown
SkyCrown is listed as licensed by the Tobique Gaming Commission. Its stated payout times are around 10–15 minutes for crypto and 1–5 days for fiat; the minimum deposit is A$30.
Ricky Casino
Ricky Casino lists crypto payouts as taking under an hour and PayID payouts as taking 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
The phrase “casino sites that accept credit card in Australia” can also blur two different meanings. It may refer to a site that makes a card option available to people in Australia, or to a casino legally permitted to offer real-money games within Australia. Those are not interchangeable descriptions. A payment method being shown or reported does not make the underlying gambling service lawful. The legal restriction applies to operators offering the games, not merely to the way a deposit is funded.
For the same reason, identifying an Amex option should not be read as a shortlist of suitable or approved operators. “Best” would require criteria beyond whether a card option has been reported, while naming services as choices could imply endorsement. The financially relevant point is more restrained: acceptance has been reported in some cases, but it is not a market-wide feature and is not a mark of legal approval.
The distinction between a casino’s cashier and its status as a gambling operator is also important. A cashier is where payment options are presented; its contents describe a transaction facility, not a licence to offer online casino games to Australians. Under the Interactive Gambling Act 2001, the operator’s provision of real-money casino games to people physically in Australia is prohibited. A displayed American Express option does not alter that rule or provide consumer protection for offshore play.
Accordingly, references to online casinos accepting credit cards should be treated as descriptions of reported payment availability, not as an invitation to deposit. Amex acceptance has been reported at some services, but it cannot be assumed for all casinos, all Australian users, or every point in time. The distinction is factual rather than cosmetic: a payment option may be described, while the service itself remains outside the lawful Australian real-money casino market.
A casino credit-card deposit is described as a short cashier transaction: American Express is selected as the payment method, card details and a deposit amount in Australian dollars are entered, and the payment is submitted. That sequence explains how the transaction is presented by a cashier; it does not establish that a payment will be accepted or that the service is lawful for Australian residents.
The legal distinction matters before any payment mechanics do. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players using offshore casinos. A description of a payment workflow should therefore not be read as a recommendation to deposit or as assurance that a transaction is permitted, protected or recoverable.
The amount is entered in AUD, so the figure shown at the point of submission is the intended deposit amount in that currency. Card details are supplied as part of the payment request. The player then submits it through the cashier, after which the payment is processed. This is the transaction sequence, not a guarantee that the account will show the funds or that the card issuer will approve the charge.
Specialist reviews describe Amex casino deposits as processing instantly. “Instant” refers to the reported processing of the deposit; it should not be treated as a universal settlement commitment or as proof that every payment reaches an account without delay. The cashier and payment provider determine how a particular transaction is handled, and a stated processing speed does not resolve whether the transaction is available to an Australian customer.
A useful distinction is between the time taken to process a payment and the amount ultimately charged. A deposit displayed in AUD may be recorded as a card transaction, while any fees depend on the terms applying to that transaction. The displayed deposit amount alone does not establish that the final card statement will contain no additional charge. The relevant figures are the submitted amount and any separately disclosed transaction fee; they should not be conflated.
Specialist reviews describe Amex deposits as generally fee-free, but that is not a fixed rule for every casino. The casino’s own payment terms determine whether it adds a charge. Where a fee applies, the total cost is the deposit amount plus that charge. If the cashier does not state the fee clearly before submission, the cost cannot be calculated from the deposit amount alone.
This distinction avoids treating two different fee positions as if they were interchangeable. A casino may impose a charge for taking a deposit, while a card transaction may have a separate treatment under its own terms. The final amount depends on the terms attached to the specific payment.
Deposit charges also need to be kept separate from withdrawal charges. A no-fee deposit does not mean that money can later be withdrawn without a fee. Specialist reviews note that withdrawal fees may apply, depending on the casino. Those charges arise on the payout side and should not be added to the cost of the deposit unless they are actually incurred. Conversely, the absence of a deposit fee says nothing about the amount or timing of a later withdrawal.
For an account record, the basic comparison is therefore between the AUD amount entered, any fee disclosed for the deposit, and the amount posted to the card. A separate withdrawal term belongs in a separate calculation. Combining the two would make the apparent cost of the initial transaction inaccurate.
A fast processing description and a no-fee description are both conditional, not guarantees. Neither changes the legal position for real-money online casino services in Australia, nor does it create consumer protection for a person using an offshore casino. The cashier sequence can explain what a payment request looks like; it cannot establish that the service is lawful, that the payment will be accepted, or that the amount shown is the only financial consequence.
Card Deposit Process
Selection
American Express is selected as the payment method in the cashier.
Entry
Card details and the deposit amount in Australian dollars are entered.
Submission
The payment is submitted through the cashier for processing.
A card payment can fail before the casino records a deposit, or it can be processed for more than the amount shown in Australian dollars. These are separate outcomes. A declined transaction does not create a completed deposit; a currency conversion charge can increase the cost of a payment that does go through.
An Australian bank may block gambling-related transactions on an Amex card at the issuer level. In that case, the restriction comes from the bank that issued the card, rather than from the amount entered or the casino’s deposit limit. The card can therefore be declined even where the cashier displays Amex as an available payment method.
A separate block may apply on the Amex side. A specialist review reports that Amex may prevent payments to a particular website, in which case an attempted deposit can be declined. A casino’s display of a credit-card option cannot establish that the transaction will be authorised: the issuer and Amex can each affect whether it proceeds.
These distinctions matter when interpreting a failed payment. A rejection does not, by itself, show that the card is invalid or that the entered amount was the cause. The restriction may be tied to gambling transactions at the issuing bank, or to the particular website under Amex’s payment controls. Those are different points in the payment chain, even though the result at the cashier may look the same.
A decline also differs financially from a completed transaction with an added charge. If the payment is refused, the intended deposit has not been credited through that transaction. If it is approved, a separate currency-conversion cost may still change the final amount charged. Treating every difference between the cashier amount and the card account as a casino fee would conflate separate causes.
Currency conversion is relevant where the card transaction is processed in a currency other than Australian dollars. A specialist review states that Amex cards incur a 3% currency-conversion fee. That figure should be treated as a reported card cost, not as a universal charge for every Amex deposit: whether conversion applies depends on the transaction’s currency, and the stated percentage does not establish that every casino or card account will apply it in the same way.
The distinction is between the deposit amount and the amount ultimately charged after conversion. If the cashier presents an AUD amount but the transaction is processed in another currency, the displayed AUD figure may not capture the full card cost. Conversely, the existence of a stated conversion fee does not mean that a fee is added to every AUD-denominated transaction. The relevant issue is the currency in which the card payment is processed.
Conversion charges also should not be confused with a casino-imposed surcharge. They arise from different parts of the transaction: one relates to currency conversion on the card side; the other, if charged, would be a separate amount applied by the operator. A single final figure on a card statement may not make that distinction obvious without looking at the transaction currency and the terms applying to the card.
For a credit-card casino payment, three questions should remain separate: whether the transaction was authorised, what currency it was processed in, and whether a conversion cost altered the final charge. The first concerns a possible block by the issuing bank or Amex. The second determines whether currency conversion is relevant. The third concerns the resulting cost rather than whether the deposit was accepted.
That separation prevents a common accounting error: assuming that a declined payment and an unexpectedly high charge are versions of the same problem. A block stops the transaction from being completed. A conversion fee affects the cost of a transaction that proceeds. The former is an authorisation issue; the latter is a pricing issue.
A credit card’s general ability to make purchases does not settle either question. For Amex, an issuer-level restriction on gambling transactions may prevent payment, and a restriction by Amex may apply to a particular website. If payment is authorised, the currency used for processing still determines whether the reported conversion fee is relevant. Acceptance at the cashier is therefore not a complete account of either approval or final cost.
The practical accounting record is the amount entered, the currency in which the payment is processed, and the final card charge. Where the transaction is declined, there is no completed deposit to reconcile against that entry. Where it is approved, a difference between the entered AUD amount and the final charge should be considered in light of currency conversion rather than automatically labelled a casino surcharge. This is a distinction between causes, not a guarantee that any payment method will be available or accepted.
Card acceptance and transaction limits are separate terms. A payment method may appear in an operator’s cashier while the permitted transaction amount differs from the amount allowed on another network. Neither point establishes that every online casino accepts that card.
A specialist review reports that Visa may be accepted by a broader range of Australian online casinos than American Express. That is a comparison reported by one review, not a guarantee of coverage across operators. Amex acceptance is therefore a narrower question than whether card payments are offered at all: a cashier that lists Visa does not, on that basis alone, confirm Amex support.
The same review reports that Amex transaction limits can be higher than those attached to Visa or Mastercard options. The distinction is about the ceiling available for a transaction, not the breadth of acceptance. A higher stated limit has no practical value where the network is not offered, and it does not show what limit applies at a particular operator. Acceptance and the permitted amount have to be treated as separate entries in the payment terms.
Reported by specialist reviews to be accepted by a broader range of Australian online casinos.
Reported to have potentially higher transaction limits than Visa or Mastercard options.
For a casino that accepts credit-card deposits, the relevant comparison is not simply “card versus no card.” It is whether the specific network is listed and what limit is attached to it. An online casino that does not offer card payments is different from one that accepts Visa but not Amex. Both may be described informally as having limited card choice, but the payment terms are not equivalent.
| Comparison | What the reported information supports | What it does not establish |
|---|---|---|
| Visa and Amex acceptance | A specialist review says Visa may be more widely accepted. | That Visa is accepted at every operator or that Amex is unavailable at most operators. |
| Amex and Visa or Mastercard limits | A specialist review says Amex limits can be higher. | A universal limit, a fixed difference, or a higher limit at any named casino. |
This comparison should not be converted into a ranking of networks. The reports describe tendencies, not a complete market schedule, and do not provide a defensible figure for the difference between card limits. A claim that one network is always accepted, or that Amex always permits a larger transaction, would go beyond what the comparison establishes.
The useful accounting distinction is straightforward: acceptance determines whether a network can be used; the operator’s stated limit determines how much may be processed through it. A broader acceptance footprint does not necessarily mean a higher transaction ceiling. Conversely, a higher ceiling reported for Amex does not make it a more widely available option. The terms need to be read independently rather than compressed into a single label such as “best card.”
A cashier listing is also not proof that every card issued under a network will work. The card option and its displayed limit describe the operator’s stated payment terms; they do not amount to a promise that each attempted transaction will be approved. For comparison purposes, the supportable conclusion is limited: one specialist review describes Visa as potentially broader in acceptance and Amex as potentially higher in transaction limits than Visa or Mastercard. Those are different advantages, and neither settles the terms for an individual operator.
There is no single American Express limit that can establish which casino is “top” for every account. A specialist review reports that online casinos set their own Amex deposit and withdrawal limits, and that those terms vary. A ranking based on one quoted limit would therefore describe an individual operator’s terms, not a market-wide standard.
A useful comparison separates the two sides of the account. The deposit limit sets how much can be placed through Amex; the withdrawal limit sets how much can be returned through that method. A casino’s terms for one do not establish its terms for the other. Comparing only a deposit figure can make an option look more flexible while saying nothing about the withdrawal side.
The relevant criterion is not the largest number in a headline. It is whether the stated Amex deposit and withdrawal limits fit the intended transaction, considered together. If a review gives only one figure, or does not make clear which direction of payment it covers, it is not enough to compare the full set of limits. The operator’s own payment terms are the material point, because that is where the applicable limits are set.
This also means that a label such as “top credit card casino” cannot be derived from Amex limits alone. The same limit may suit one transaction and not another; a higher limit is not automatically a better fit. Without comparable terms for both deposits and withdrawals, a league table would imply a precision the underlying comparison does not support.
The practical test is consistency of information: check that the terms refer specifically to American Express, distinguish deposits from withdrawals, and can be compared on the same basis. Where a casino’s published terms do not provide that clarity, its position relative to another option remains uncertain. A ranking should not fill that gap with assumptions.
For Australian readers, this is a comparison of payment terms, not an endorsement of any casino. The limit attached to a payment method is only one part of its terms and cannot, by itself, establish that an operator is suitable or lawful for use in Australia. A neat ranking would be convenient. It would also be doing more work than the numbers allow.
The legal distinction is between the operator’s conduct and the player’s. Under the Interactive Gambling Act 2001, an operator must not provide real-money online casino games to people in Australia. The prohibition covers casino-style services such as poker, table games and pokies; it is not limited to businesses based in Australia. A foreign address or offshore licence does not make offering those services to people in Australia lawful.
The Act does not explicitly make a player’s use of an offshore casino a criminal offence. That distinction does not turn the service into a lawful or protected transaction. Australian consumer law does not protect players who use offshore casinos, so the usual domestic consumer protections cannot be assumed to apply if a dispute arises. The operator’s location and terms may also leave a player with limited practical means of resolving a problem.
The Australian Communications and Media Authority (ACMA) enforces the Interactive Gambling Act. Its role concerns compliance with the law by service providers; it does not convert an offshore casino into an approved Australian service. Illegal services may be subject to enforcement and access restrictions. A site appearing online, or accepting a payment from someone in Australia, is not evidence that it is authorised to offer casino games here.
That context matters when a page describes online casinos that accept credit cards for real-money play. Payment acceptance is a separate question from legal permission to provide the underlying gambling service. A card transaction does not establish that the operator may lawfully serve Australian customers, nor does it give the customer consumer-law protection for the gambling activity. The payment method cannot alter the legal status of the service.
For Australian audiences, information about card acceptance should therefore not be read as an invitation or recommendation to use an offshore casino. The relevant legal position is that operators are prohibited from providing real-money online casino games to people in Australia, while the Act does not explicitly criminalise players for using offshore sites. Those two points can coexist: the operator’s offer is prohibited, but the player’s position is not the same as the operator’s.
The practical conclusion is narrow. A site’s claims about real-money play, payment options or an overseas licence do not establish lawful availability in Australia. ACMA is the enforcing authority, and Australian consumer law does not supply protection for transactions with offshore casinos. No card brand changes those conditions.
An Amex deposit does not establish that winnings can be returned to the same card. A prior deposit using American Express is a condition for an Amex withdrawal, but it is not a guarantee that the casino will offer that payout route. The cashier’s withdrawal options and the operator’s terms determine whether the card can be selected.
A specialist review reports that some casinos do not send winnings back to American Express, while others may attach an additional withdrawal fee. These are operator-specific terms, not a uniform rule for Australian customers. If Amex is unavailable, the available alternative and any associated cost depend on the casino’s stated withdrawal methods. The balance shown in an account therefore does not, by itself, establish how much will arrive on the card or when.
Timing also needs to be read as a reported estimate rather than a fixed service standard. A specialist review gives a clearance period of up to five days for Amex casino withdrawals. That figure should not be treated as a guaranteed deadline: the casino’s processing and the card transaction’s clearance are separate stages, and the stated period may not describe every operator or account. The applicable withdrawal terms are the relevant reference for a particular transaction.
The practical distinction is between eligibility, fees and timing. Eligibility depends on the prior Amex deposit and whether the casino permits withdrawals to that card. A fee may reduce the amount returned. Clearance time affects when the funds become available, not the amount authorised for withdrawal. Each term should be considered separately; a card accepted for deposits does not settle any of the three withdrawal questions.
There is also a market-level limitation on relying on an offshore casino’s payout terms. Australian consumer law does not protect players who use offshore casinos. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, so a stated card payout route should not be confused with domestic consumer protection.
A specialist review reports that some online casinos do not accept American Express. That is a limited, time-sensitive observation, not evidence of a market-wide rule or a permanent policy. Acceptance can differ between operators, so the label “casino accepting credit card” does not establish that Amex is among the available card methods.
The distinction is between a card network being supported and a particular transaction being approved. If an operator does not list Amex as a payment option, the card is not accepted there for deposits. That is different from an Amex payment option being present but a particular payment failing. The first concerns the operator’s available methods; the second concerns a transaction attempt. Treating both as the same issue obscures where the limitation sits.
Acceptance differs between operators; if an operator does not list Amex in the cashier, the card is not accepted for deposits at that specific service.
A general claim about casinos accepting credit cards is therefore too broad to settle Amex availability. Credit-card acceptance does not mean acceptance of every network, and a statement about one operator cannot establish the position at another. The relevant detail is the named method in the operator’s own current payment information, rather than a general description of cards.
This makes acceptance a specific term to verify, not a feature that can be assumed from the presence of credit-card payments. A specialist review can indicate that an acceptance gap exists, but its information may become outdated as payment options change. It should not be treated as a current guarantee about any particular cashier. Nor does a reported gap, by itself, establish why an operator has chosen not to list Amex. No single explanation can be attached to all such cases on the basis of the reported information.
The practical distinction is narrow: some operators may not offer Amex, while others may list it. Any broader claim about availability needs to be tied to the operator and the current payment terms.
Australian consumers are accustomed to moving between cards, mobile wallets and services connected to bank accounts, such as PayPal. A payment method does not have to be a credit card to be familiar or widely used.
Google Pay and Apple Pay are accepted almost everywhere in Australia in everyday commerce. That broad retail acceptance does not establish that either wallet is available for online gambling payments, or that an online casino can lawfully offer such a transaction to someone in Australia. Payment availability and legal permission are separate questions.
For someone looking for an online casino payment without a credit card, the distinction matters: a wallet or bank-linked service may be a non-card option in general, but that does not make an offshore gambling service lawful or protected. Australian consumer law does not protect people who use offshore casinos. The presence of a familiar payment logo is not a substitute for that assessment.
The practical comparison is therefore about payment categories, not a promise that a particular method will work at a particular gambling site. Cards, mobile wallets and bank-linked services are all part of Australian consumers’ everyday payment mix. Their general acceptance should not be read as confirmation of a gambling operator’s eligibility to serve Australian residents.
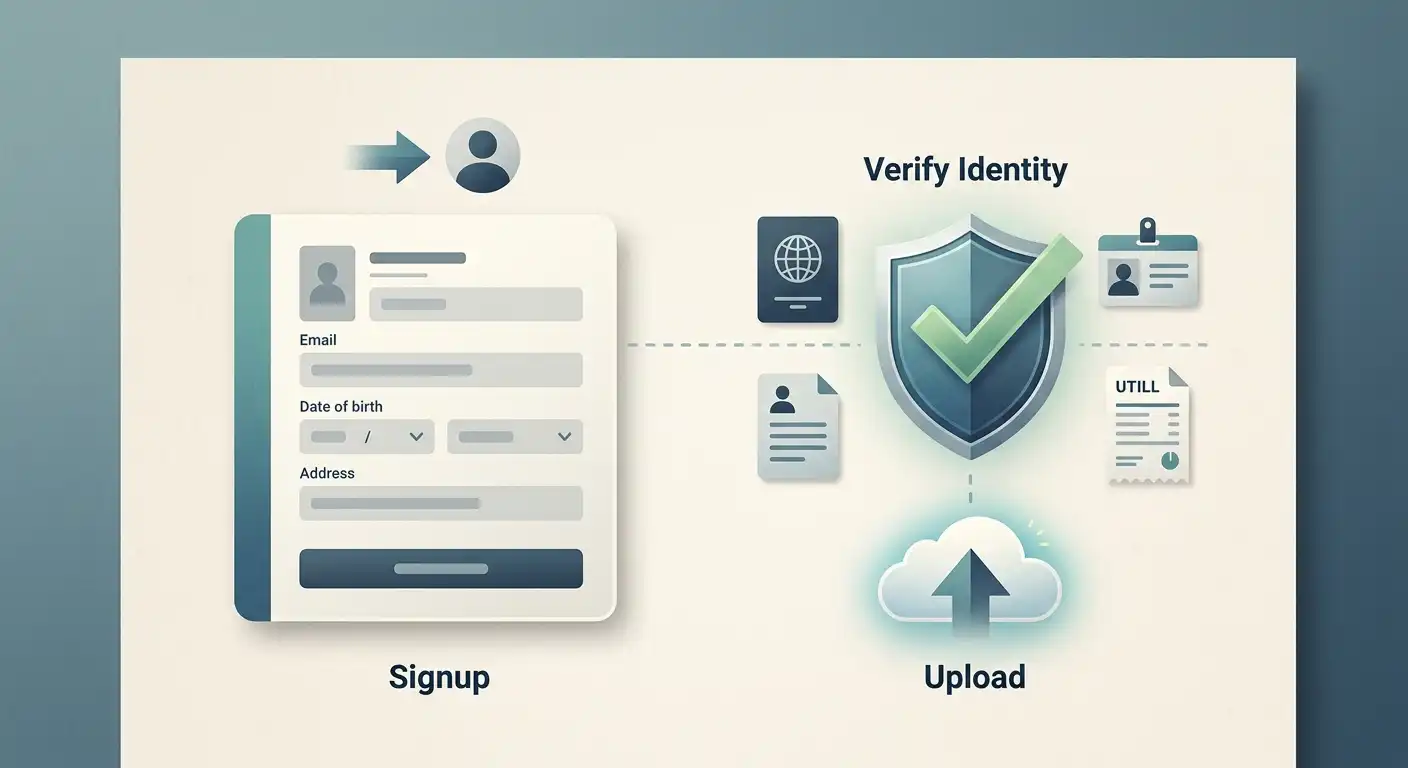
An account may need to pass a Know Your Customer assessment before a financial transaction is processed. This is an account-verification prerequisite, separate from the payment method itself: entering card details does not complete the assessment. Until the operator has finished its checks, a requested transaction may remain subject to that step.
The required process is set by the operator. Its account terms should explain what verification involves and when it must be completed. No particular document list or processing time applies across all online casinos, so those details cannot be treated as standard.
Fee claims also need careful separation. A specialist review describes American Express gambling transactions as free, but that is not a universal fee schedule. Charges depend on the operator’s terms, and a withdrawal may carry a fee even where a deposit does not. The amount to assess is therefore the fee stated for the specific transaction, not a general claim about Amex.
For Australians, the legal context matters before any account or payment step: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The Australian Communications and Media Authority enforces the Act. Australian consumer law does not protect players using offshore casinos. Verification or a successful card transaction does not change either point.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are reported to support Amex deposits. Payment availability does not mean these services are authorised to offer online casino games in Australia.
Check the casino cashier for American Express as a deposit option and review its payment terms. Acceptance can vary between services and may change.
Casinos typically require customers to complete a Know Your Customer assessment before financial transactions. Australian banks may also block gambling-related Amex payments.
Amex deposits are typically fee-free, but a casino may apply a 1.5% surcharge, and Amex currency conversion can incur a 3% fee. Withdrawal fees may also apply, depending on the casino.
Look for American Express in the casino’s cashier and check its payment terms. A listed option does not guarantee that a particular transaction will be approved; Amex or the issuing bank may block it.
Australian consumer law does not protect players using offshore casinos, and a displayed Amex option does not make the service lawful. The Interactive Gambling Act 2001 prohibits operators from offering real-money online casino games to people in Australia.
Written by the editors at Norco Casino.