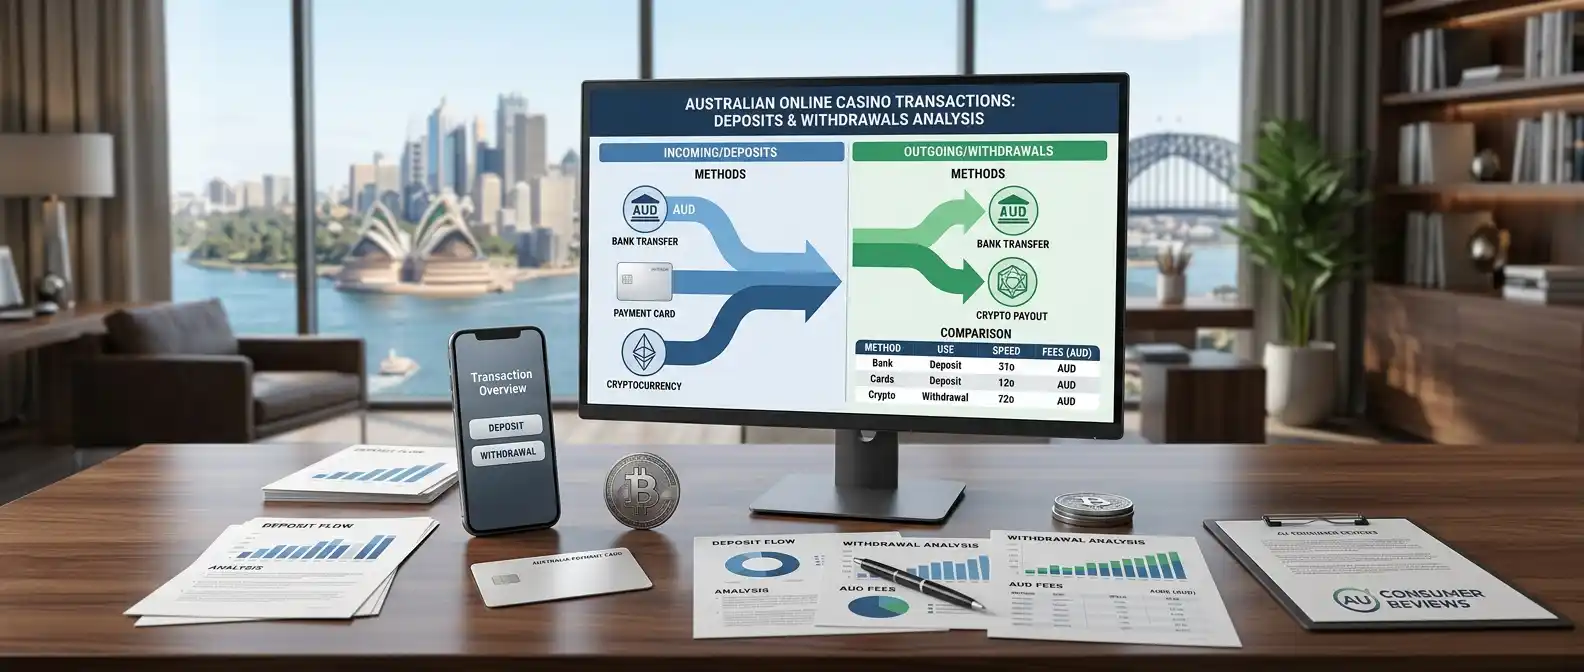
The guide separates payment acceptance from legality, deposit costs and withdrawal claims, which require distinct evidence.
A payment method does not determine whether an online casino may lawfully serve people in Australia. The legal question comes first: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. That includes casino-style offerings such as poker, blackjack, roulette and pokies. A site’s overseas location, payment options or description of its services does not remove that restriction.
The Act places the relevant prohibition on operators. It does not explicitly make an individual player’s use of an offshore casino a criminal offence. Those are separate parts of the legal picture: the rules restrict the provision of the service to Australian residents, while the Act does not expressly criminalise the player for using an offshore site. That distinction should not be mistaken for approval, local oversight or a guarantee of consumer protection.
The Australian Communications and Media Authority, known as ACMA, enforces the Act. Enforcement is directed at prohibited interactive gambling services offered to people in Australia. The maximum daily penalties set out under the law are substantial: $360,000 for an individual and $1.8 million for a body corporate. These penalties concern violations of the Act; they should not be presented as fines imposed on players simply for using an offshore casino.
For Australian players considering paysafecard, a useful shortlist should be a starting point for checking which sites currently support that payment method and what their terms are. The details below highlight only the information available for each operator.
Roby Casino
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd.
Playfina Casino
Playfina Casino is listed with a Curacao eGaming licence held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
WinSpirit Casino
WinSpirit Casino is listed under Curacao eGaming licence OGL/2024/923/0383, issued to Antillephone N.V. Its minimum deposit is A$30.
Lucky Dreams
Lucky Dreams is listed with a Curacao licence. The stated minimum deposit is A$20 via POLi.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence, held by TechSolutions Group N.V.
House of Pokies
House of Pokies lists an international iGaming licence, though the source does not name the jurisdiction. PayID payouts are stated as taking 1–24 hours; the minimum deposit is A$30, or A$10 via PayID.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence.
SkyCrown
SkyCrown is listed with a Tobique Gaming Commission licence. Its stated payout times are around 10–15 minutes for crypto and 1–5 days for fiat; the minimum deposit is A$30.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Interest in Paysafecard alongside casino or pokies terms does not settle the legal status of a service. A search for an Australian online casino that accepts Paysafecard is a payment-related description, not evidence that the operator is permitted to offer real-money casino games to people in Australia. Nor does the appearance of a payment option establish that a casino is authorised or subject to Australian consumer protections.
The same distinction applies to mobile access. A casino site that can be opened on a phone is not thereby a locally permitted service. Access through a browser or an app changes how a site is reached, not the legal boundary governing the operator’s offer. Where a service provides prohibited real-money casino games to people in Australia, its payment branding does not alter that classification.
Offshore sites may be encountered in searches, but Australian enforcement includes active efforts to restrict access to prohibited services. Their appearance online should not be read as proof that they are lawful for operators to provide in this market. Availability can also be an unstable basis for a financial decision: a service being visible at one point does not establish that it will remain reachable or that the conditions attached to an account will be enforceable locally.
The absence of an explicit player offence is not the same as protection when a dispute arises. Australian consumer law does not protect people who use offshore casinos. If an account is restricted, a payment is disputed or winnings are withheld, the fact that the player is not expressly criminalised under the Interactive Gambling Act does not provide a local consumer-law remedy for that offshore transaction.
This distinction matters because legal responsibility and practical recourse are different questions. The Act’s prohibition addresses what operators may offer to people in Australia. The limited protection for a person who chooses an offshore service concerns what support may be available if the relationship with that operator breaks down. Neither point should be collapsed into a claim that offshore play is locally regulated.
Descriptions such as “Australian casino” can refer to an audience, a currency setting or a site’s marketing language. They do not, by themselves, show that the operator is based in Australia or has permission to provide real-money casino services here. The governing issue remains the service offered to people physically in Australia, not the wording used in a website label.
For the same reason, a list of payment methods cannot function as a legal checklist. A cashier displaying a familiar payment brand would tell only part of the story, and it would not override the Act. Payment acceptance, if stated by a site, is separate from whether the operator may lawfully provide the underlying casino service to Australian residents.
The boundary is therefore straightforward even when the online presentation is not: the law prohibits operators from offering real-money online casino games to people in Australia; ACMA is responsible for enforcement; and the Act does not explicitly criminalise players for using offshore sites. That last point does not make offshore casinos locally lawful, locally supervised or covered by Australian consumer protection. A payment method cannot change any of those conclusions.
A proposed deposit amount is not the same as a confirmed deposit condition. A figure such as $10 describes the amount someone may wish to put into an account; it does not, by itself, establish that a particular cashier will accept that amount or that the final debit will equal it. The useful comparison is between the amount entered, any charge applied to the transaction, and the amount credited after payment. Each part affects the cost, and none should be inferred from the payment method’s name alone.
The first figure to check is the minimum amount accepted for a deposit. That is an operator-set condition, not a universal property of Paysafecard. A stated minimum may also differ from the amount that can be selected in the cashier, so the transaction screen and the applicable payment terms need to agree. A search for a ten-dollar Paysafecard deposit does not establish that ten dollars is an available option. It only identifies a target amount to compare with the conditions shown for the specific account and transaction.
The maximum amount is a separate condition. It can matter even when the intended deposit is modest: a cashier may set transaction boundaries, and payment services can have their own conditions. The amount entered should therefore be assessed against the actual limits displayed for the transaction, rather than against a general description of Paysafecard. No useful cost calculation can be completed from a minimum alone if the permitted upper boundary or the applicable transaction conditions are unclear.
Fees require the same separation. A deposit may involve a charge imposed by the casino, by a payment provider, or through currency conversion. Those are different cost sources and should not be collapsed into one vague label such as “free.” The relevant figure is the total amount taken from the payment balance compared with the amount credited to the casino account. If the transaction is in a currency other than Australian dollars, the conversion basis and any associated charge also affect the final cost. A displayed deposit amount is not necessarily the final amount paid.
The cashier is where the transaction’s practical terms should be visible before submission: the selected method, the amount, the currency, and any stated charge. The terms attached to the payment should be checked alongside the amount shown on screen. If the amount entered differs from the amount that will be charged, or if a fee is presented separately, the final debit is the figure relevant to the budget. A payment description that omits one of these elements does not make that element costless; it leaves the calculation incomplete.
Processing time is not a price, but it can affect the practical value of a payment route. A deposit described as pending is not equivalent to a completed credit, and a stated processing estimate is not the same as a confirmed transaction. Timing should be treated as a distinct condition rather than assumed from the speed associated with another payment method. A claim about Paysafecard deposits needs to apply to the casino, account status and transaction in question, not merely to a general description of prepaid payments.
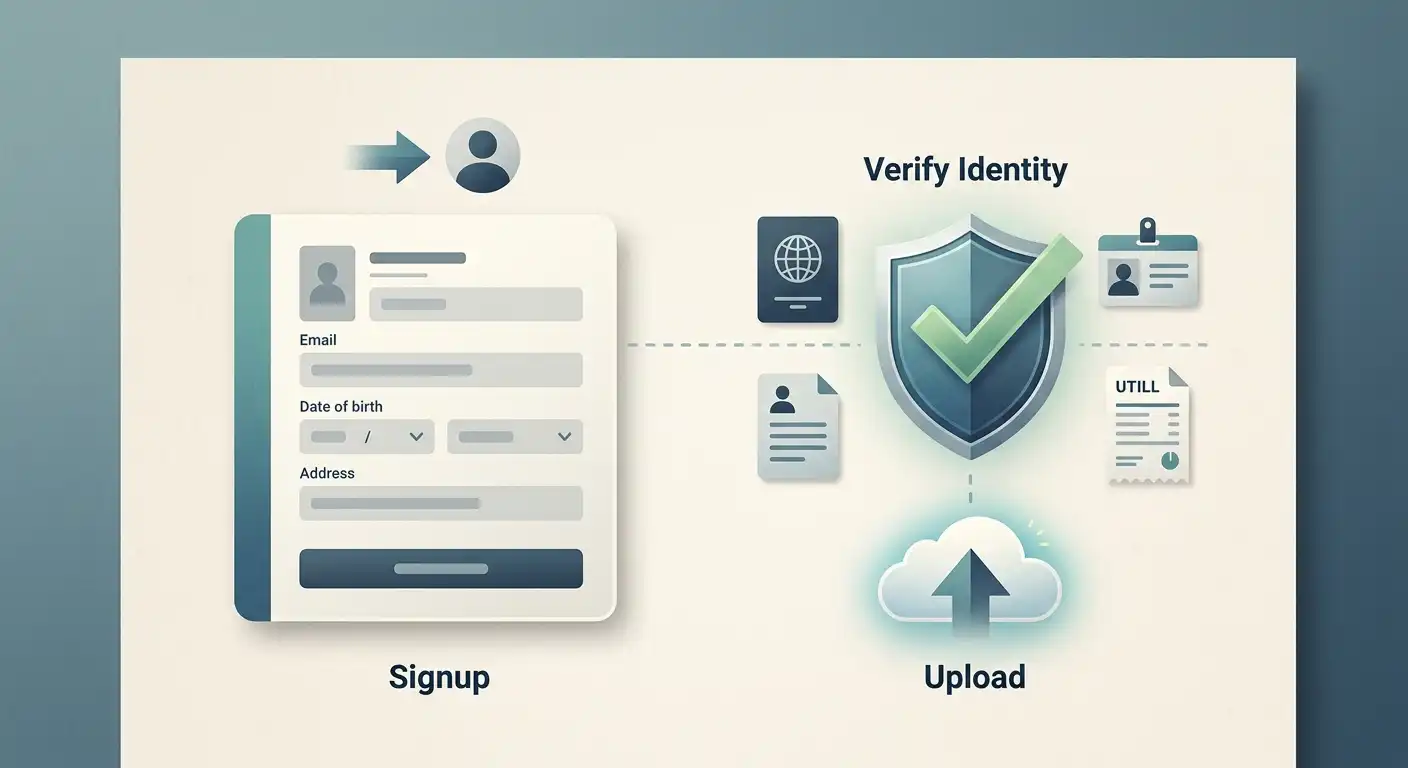
Account verification may also affect whether a financial transaction can proceed. Online casinos commonly ask customers to complete identity checks before allowing financial activity. That assessment is separate from the deposit amount and fee: satisfying a payment screen does not itself establish that account checks are complete. The status of verification can therefore affect when a transaction is available, without changing the nominal amount entered.
A sound cost comparison records the intended deposit, the minimum and maximum permitted amounts, the currency, every stated fee, the amount ultimately charged, and the amount credited. These fields should be taken from the terms that apply at the point of payment, not inferred from a headline or from another operator’s conditions. If one field is absent, a precise final cost cannot be calculated from the remaining fields alone. That is a calculation limit, not a reason to substitute an assumed amount.
For a Paysafecard deposit, the decisive number is therefore not merely the amount typed into a form. It is the final debit under the specific cashier’s displayed conditions, weighed against the credited balance. Until those figures align clearly, a proposed deposit amount remains a budget target rather than a verified transaction cost.
A Paysafecard deposit and a casino withdrawal are separate transactions. Seeing a payment method among deposit options does not establish that it can also receive winnings. The cashier may present different methods for money going in and money coming out, so the two directions cannot be treated as interchangeable.
That distinction matters when a payment is described as “instant”. The word may refer to depositing, account crediting, or a stage of a withdrawal; it does not identify which stage, or establish when funds become available outside the casino. Without a stated payout route and its conditions, “instant Paysafecard withdrawal” is not a usable estimate of the time to receive money.
A deposit records funds moving into an account. A withdrawal requires the operator to approve a payout and send it through an available route. The method selected for the first transaction does not, on its own, determine the method for the second. A casino could require a different route, or could offer no Paysafecard withdrawal option. Neither possibility can be resolved by the deposit choice alone.
The relevant terms are specific to the operator and the account. They may distinguish between the method used to fund an account and the destination permitted for a payout. Any conditions attached to withdrawals also need to be read as withdrawal conditions, not inferred from deposit instructions. A payment logo in a deposit cashier is not a promise about returning funds.
This is why a request for the best instant Paysafecard withdrawal casino in Australia cannot be answered by comparing deposit availability. To assess a payout claim, the applicable terms would need to identify Paysafecard as a withdrawal route and explain what “instant” measures. Without both, the phrase gives no reliable basis for calculating when winnings would arrive.
A withdrawal is not a single moment. A request may be submitted, reviewed, approved, and then sent through a payment channel. These are distinct stages. A claim about one stage does not establish the duration of the others, and no general meaning of “instant” can be assigned without the operator’s stated terms.
The distinction also applies to searches for instant Paysafecard pokies or real-money play. A game or deposit description would not prove that winnings can be returned through the same payment method, or that the withdrawal is immediate. Nor does the presence of a no-deposit offer establish any payout route; promotional conditions and payment arrangements are separate matters.
For a financial comparison, the final amount received and the time to receipt matter more than a label. Those figures depend on the actual payout terms and any conditions that apply to the account. A deposit method alone supplies neither figure. Treating it as a withdrawal guarantee would convert an unconfirmed assumption into a money decision.
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. That limitation is relevant to payment claims as well as other account terms: a description of a withdrawal method should not be mistaken for a local consumer safeguard.
Accordingly, Paysafecard should not be treated as an instant payout route merely because a casino accepts it for deposits. A withdrawal claim needs to stand on its own terms: the route, the applicable conditions, and the meaning of any stated timing. Without those, “instant” is packaging, not a calculated arrival time.
Paysafecard acceptance is a claim about a particular operator’s payment arrangements, not a general feature of online casinos. A site’s description, a payment logo or a third-party listing does not, by itself, establish that a Paysafecard transaction is available to someone in Australia. The practical question is whether the payment option is presented for the relevant account and location at the point a transaction is considered.
The distinction matters because payment availability can be described in broad terms while depending on details that are not visible in a headline. A logo may indicate a payment brand is discussed somewhere on a site, rather than confirming that it can be used for a specific transaction. Likewise, a page that refers to Paysafecard does not necessarily establish that the method is enabled for Australian users. An acceptance claim needs to be specific enough to distinguish general mention from an available route.
“Best” does not resolve that uncertainty. A ranking can only compare sites on a meaningful basis if the underlying conditions are clear and comparable. Without confirmation that Paysafecard is accepted for the relevant Australian account, a ranking based on that feature has no reliable starting point. A polished label is not a payment term.
The wording also needs precision. “Accepts Paysafecard” could mean that a brand appears in a list of payment methods, that a cashier displays it, or that a transaction can actually be completed. Those are different levels of confirmation. A statement about deposits should not be read as confirmation about every other payment function, and a general mention of a payment service should not be treated as proof of a working option.
This payment question is separate from the legal status of offshore casino services. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in Australia. The fact that a payment method is mentioned, or that a transaction might be displayed, does not alter that restriction. Nor does it create Australian consumer protection for someone using an offshore casino: Australian consumer law does not protect players in that situation.
The distinction is consequential. Payment branding is not a sign that an operator is authorised to provide online casino games in Australia, and the presence of a cashier option would not change the legal position. A payment method and the service accepting it answer different questions; treating one as proof of the other confuses a transaction detail with a regulatory status.
For Australian players, the defensible reading of a Paysafecard claim is therefore narrow: it must refer to a clearly identified operator, the relevant location and a specific transaction route before it can be treated as confirmed. A broad statement that casino sites take Paysafecard cannot establish that a particular Australian user can use it. This is not a question of choosing the strongest-sounding label; it is a question of whether the stated condition applies in the specific case.
That standard also prevents a common category error. General acceptance of electronic payments in Australia says nothing about whether Paysafecard is accepted by an online casino, and acceptance by one merchant says nothing about another. Each claim stands or falls on its own terms. A list that presents acceptance as universal would erase the very distinction on which the claim depends.
A payment method and a game category describe different parts of an online service. Paysafecard relates to how a transaction might be made; a category describes the kind of content offered. One label does not establish anything about the other. A casino page grouped under a payment heading therefore cannot, by that wording alone, establish which games are available or how they are classified.
This distinction matters when a site presents payment information beside its game catalogue. A cashier can list transaction methods, while a separate lobby can organise content using its own labels. Those labels are not payment terms, and a payment logo is not evidence that every part of the site shares the same conditions. Treating the two as interchangeable turns a navigation label into a claim it cannot carry.
The same separation applies to bonuses. A promotional label may refer to an account offer or other site condition, not to a particular game category. Its presence does not show that a payment method qualifies, that a game contributes to an offer, or that any particular terms apply. Those are distinct questions, and bundling them under one heading can obscure the actual conditions. A bonus label is not a substitute for the wording attached to the offer.
A game catalogue can also use categories for browsing rather than for describing payment compatibility. A category may group content by format, theme, or other site-defined criteria. Those classifications do not establish that a given payment option applies across the category. Nor does a payment label establish that all content is available to a person in a particular location. The label and the underlying service are separate matters.
For the same reason, a list of sites arranged around a payment method would not, by itself, be a reliable catalogue of game categories. The organisation of such a list could describe how its entries are grouped, but it would not settle which content appears on each site or what conditions apply to it. A heading can signal a topic; it cannot replace the terms governing the service.
The useful distinction is narrow: payment information concerns transaction handling, while game-category information concerns content. A combined page may place both in view, but proximity is not proof of a connection. A reader assessing a category label should not treat it as evidence about a payment route, and a payment reference should not be read as confirmation of a particular catalogue.
This is also why broad phrases such as “Paysafecard games” can be imprecise. They may refer to games displayed by a site that mentions the payment method, rather than to a recognised category with specific shared features. Without a clear definition, the phrase collapses two separate subjects into one. The result is a description that sounds specific but does not identify what is actually being described.
Game categories, promotional terms, payment methods, and site access each require their own context. Keeping those labels separate avoids attributing a feature of one part of a service to another. A category name does not determine payment conditions, and payment wording does not define the content catalogue.
Payment habits in Australia provide context, not proof of what an online gambling service accepts. Contactless cards and mobile wallets such as Google Pay and Apple Pay are common for everyday purchases. Consumers are also accustomed to moving between cards, mobile wallets and bank-linked services such as PayPal. Those habits do not establish that any of these methods, or Paysafecard, can be used for a particular casino payment.
A payment option must be assessed at the level of the service and transaction. The fact that a method is familiar in ordinary commerce says nothing about whether it is available for a gambling transaction. Nor does a general label such as “Paysafecard casino payment” establish which games or payment routes are supported. Payment choice and game access are separate questions; neither follows automatically from the other.
Customer checks are another condition in the transaction flow. Online casinos commonly require identity and customer information to be assessed before they process financial activity. This Know Your Customer review is a compliance step, not a payment method. It can affect whether an account is ready for transactions, but it does not determine which payment options are available or what their terms are.
That distinction matters when comparing payment choices. A payment method can be familiar to Australian consumers without being usable for gambling, while a customer check can apply regardless of the method selected. Neither general payment habits nor completion of an identity assessment establishes Paysafecard acceptance, game compatibility, or any specific payment condition.
There is also a consumer-protection limitation: Australian consumer law does not protect players using offshore casinos. That is a material risk, not a minor qualification to a payment comparison.
The practical accounting point is narrow: everyday familiarity, casino availability and transaction verification are different matters. A method’s presence in a general payment landscape cannot be treated as evidence that it is offered for casino use. Likewise, a completed customer check should not be read as confirmation of a particular payment route.
Online casinos commonly require identity and customer information to be assessed before processing financial activity. This compliance step can affect whether an account is ready for transactions, regardless of the payment method selected.
A Paysafecard deposit and a Paysafecard withdrawal are separate transaction questions. Seeing a payment method listed for deposits would not, by itself, establish that winnings can be returned to a Paysafecard account. The cashier’s withdrawal options and the operator’s applicable terms would need to state that route expressly.
That distinction matters because the word “Paysafecard” can describe a way to fund an account without describing how money leaves it. A withdrawal method, eligibility rules, processing stages and any charges are separate terms. None should be inferred from a deposit label or from the general availability of a payment brand.
For any proposed payout route, the relevant terms would need to identify whether Paysafecard is supported for withdrawals, what account or instrument receives the funds, whether prior use of that method is required, and whether identity or account checks affect release. Online casinos typically require customers to complete a Know Your Customer assessment before financial transactions. A submitted withdrawal request is therefore not, on its own, proof of a completed payment or a particular arrival date.
Nor does a phrase such as “all Paysafecard casinos” establish that every operator supports the same payment flow. A method name is not a payout policy.
There is also a separate Australian consumer-protection issue. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and Australian consumer law does not protect players who use offshore casinos. Payment descriptions do not change that position or create a protected route for recovering winnings.
Accordingly, no specific Paysafecard withdrawal path or timeline should be treated as established without clear, applicable terms for the transaction. Deposit access, withdrawal eligibility and payout completion are distinct conditions; combining them into a single claim would conceal rather than clarify the payment arrangement.
A Paysafecard logo or a general mention of the payment method does not, by itself, establish that a particular casino accepts it. Acceptance is a claim about a specific operator and its current payment arrangements, not a general feature of the Australian market. A casino Paysafecard listing therefore needs to be checked against information that identifies the operator and the relevant service.
The useful distinction is between a payment method being discussed and its availability being demonstrated. A clear acceptance claim would need to name the casino and show Paysafecard as an available option for Australian accounts. Without that connection, a broad statement that casino sites accept Paysafecard cannot be applied to any particular operator. Familiarity with other payment methods in Australia does not fill the gap: card and mobile-wallet habits say nothing about Paysafecard at a casino.
The same standard applies to phrases such as “Paysafecard casino Australia” or “Paysafecard accepted casino”. They describe a category someone may be looking for, not a verified list of operators. Nor does a casino’s general mention of prepaid payments establish that Paysafecard itself is supported. The payment method has to be identified, and the claim has to relate to the specific casino rather than to online payments in general.
This matters because acceptance is not a transferable property. A statement about one operator cannot establish that another casino supports the same method, and an old or unqualified reference cannot settle present availability. The practical result is a narrow one: no particular casino can be identified as a confirmed Paysafecard option on the basis of a general category claim.
No, a logo or general mention does not establish acceptance for a specific operator or Australian account; it must be verified in the actual cashier.
There is no universal answer; availability depends on the specific operator's current payment arrangements and terms.
No, general payment habits in Australia or the use of other services like Google Pay do not establish that a specific casino accepts Paysafecard.
For the same reason, the phrase “can you use Paysafecard at a casino” has no universal yes-or-no answer. It depends on an operator-specific acceptance claim that can be checked, rather than inferred from the payment method’s existence or from the habits of Australian consumers. A Paysafecard casino label is not the transaction condition itself; the specific operator’s stated payment options are what would establish that point.
For an Australian resident, the question of whether an offshore casino accepts Paysafecard sits within a market where consumer protection is limited. Australian consumer law does not protect players who use offshore casinos. A payment option shown on a site therefore does not provide the safeguards associated with a locally regulated casino service.
The legal distinction is between the operator and the player. The Interactive Gambling Act 2001 makes it unlawful for operators to provide online casino games to people in Australia. The Act does not expressly make an individual player’s use of an offshore site a criminal offence. That difference is narrow: it does not make the service lawful for the operator, nor does it create a consumer remedy if a transaction or dispute goes badly.
This matters when assessing claims about an Australian casino using Paysafecard. A site’s description of itself as Australian-facing, or its display of a payment brand, does not establish that the service is authorised in Australia or that Australian consumer protections apply. The payment method and the legal position are separate questions; one cannot answer the other.
For Paysafecard specifically, an acceptance claim needs to be tied to the particular operator and its current terms. Even then, apparent availability would not change the consumer-protection position for an offshore casino. If a dispute concerns account access, a balance, or a payment, the fact that the player is not expressly criminalised does not guarantee a route to recover funds or obtain local support.
The distinction is consequential rather than technical. A payment label may describe how a site proposes to take funds; it does not establish that the underlying casino service is lawful for Australian operators to provide, or that the customer has Australian consumer-law protection. Those points should remain separate when interpreting any statement about Paysafecard and an Australian-facing casino.
A payment method name is not a complete description of a transaction. For a Paysafecard casino payment, the name alone would not specify whether that option is available, how a payment is initiated, what information is required, or how the amount is handled in Australian dollars. Those are separate terms, not details that can be inferred from the method’s label.
The same distinction applies to cost. A payment route does not, by itself, determine whether a charge applies, whether currency conversion is involved, or whether the amount displayed before confirmation is the final amount debited. These conditions need to be stated for the particular transaction; assumptions based on another payment method do not fill the gap.
Nor does a general description establish the sequence between selecting a method, authorising a payment and seeing a balance updated. Each is a distinct stage. A payment authorisation is not necessarily the same thing as a completed transaction, and a displayed payment option is not proof that a transaction will be accepted.
The practical accounting question is therefore not simply whether a casino says it can accept Paysafecard. It is what amount would leave the payer, what amount would be credited, and which conditions apply at each step. Without those terms, there is no sound basis for calculating the cost of a payment or treating a method label as a confirmed route.
This distinction does not change the Australian legal position. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. A payment method does not alter either point or make an otherwise prohibited service lawful.
Check the casino’s cashier for American Express as a deposit option. If it is listed, select it, enter your card details and deposit amount in AUD, and submit the payment.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as accepting Amex deposits for Australian players.
Amex deposits typically have no fee, but a casino may apply a 1.5% surcharge. Amex cards can also incur a 3% currency conversion fee.
Look for American Express in the casino’s cashier before depositing. Acceptance can vary by casino, and a payment may still be declined if Amex or your Australian bank blocks transactions to that site.
Each casino sets its own Amex deposit and withdrawal limits, so check the limits shown in its cashier or payment terms before transacting. Amex limits are usually higher than those for Mastercard and Visa.
Some casinos allow Amex withdrawals, usually only if you previously deposited with Amex; others do not. Where available, a withdrawal can take up to five days to clear and may incur a fee.
Published by the Norco Casino team.