A PayID transfer can move in real time only after the casino releases funds, while checks and review shape the wait beforehand.
“Instant” describes the transfer after funds have been released; it does not mean that a withdrawal request arrives in a bank account the moment it is submitted. A request and a payment are separate events. The first is handled by the operator. The second moves through the payment system only after release.
PayID is Australia’s bank-to-bank payment system, operating through the New Payments Platform (NPP). Transfers through the Osko network are processed in real time. That speed applies to the movement of a released payment between accounts. It does not set the time an operator takes to review a request or decide that funds are ready to leave its system.
A useful way to read a stated payout time is to identify its starting point. If the clock begins when the operator releases the funds, it measures the payment phase. If it begins when a withdrawal is submitted, it includes both the operator’s handling and the subsequent transfer. Those are not equivalent measures, even when both are described as an instant PayID withdrawal.
PayID withdrawal speed can vary, so check the stated payout details and any deposit conditions before choosing a casino. This list highlights the information available for each operator relevant to an Australia-focused PayID search.
Roby Casino
Roby Casino is listed under a Curaçao eGaming licence held by Roby Games Ltd. No PayID payout speed is specified here.
Playfina Casino
Playfina Casino is licensed by Curaçao eGaming through Hollycorn N.V., which has held the licence since 2017. The minimum deposit is A$20–30, depending on the offer; no PayID payout speed is specified.
WinSpirit Casino
WinSpirit Casino is licensed by Antillephone N.V. under Curaçao licence OGL/2024/923/0383. Its stated minimum deposit is A$30; no PayID payout speed is specified.
Lucky Dreams
Lucky Dreams is listed with a Curaçao licence and a A$20 minimum deposit via POLi. No PayID payout speed is specified.
Bizzo Casino
Bizzo Casino is listed under the Curaçao Gaming Control Board, with TechSolutions Group N.V. named as the operator. No PayID payout speed is specified.
House of Pokies
House of Pokies lists PayID payouts at 1–24 hours. Its minimum deposit is A$30, with PayID deposits from A$10; the licence jurisdiction is not named in the source.
7Bit Casino
7Bit Casino is listed as Curaçao-licensed and operated by Dama N.V. No PayID payout speed is specified.
Golden Pokies
Golden Pokies is listed with a Curaçao licence. No PayID payout speed is specified.
SkyCrown
SkyCrown is licensed by the Tobique Gaming Commission. Its stated payout speeds are around 10–15 minutes for crypto and 1–5 days for fiat; the minimum deposit is A$30.
Ricky Casino
Ricky Casino lists PayID payouts at 1–3 business days and crypto payouts in under 1 hour. The minimum deposit is A$20, or A$30 to qualify for the bonus.
The distinction can be set out as a simple sequence:
Only the final stage is governed by the real-time transfer capability. Before release, the payment has not entered that stage. A rapid bank-to-bank system cannot make an unapproved request move, just as a fast road cannot shorten the time a parcel sits in a dispatch room. The infrastructure may be immediate; the hand-off remains a separate condition.
A specialist review has described funds moving instantly once an operator releases a PayID withdrawal. Read narrowly, that is a statement about the payment leg, not a promise about the complete request-to-receipt period. The distinction matters because a headline can compress several separate steps into one attractive word. The word “instant” does not identify which step is being timed unless the conditions are stated.
For a clear comparison, the start and end points need to be explicit. “From approval to account credit” describes a narrower interval than “from request to account credit”. “After release” is narrower still if approval and release are separate actions. Without those boundaries, an instant label says little about the elapsed time a person experiences from submitting a request to seeing the balance arrive.
The same logic applies when a payment route is described as real time. That term concerns how the network handles a payment once it receives it. It does not mean every participating service sends funds immediately, nor does it erase steps that occur before transmission. The transfer system and the operator’s withdrawal process perform different functions; assigning the network’s speed to the entire process confuses the two.
This separation also explains why a PayID withdrawal may be pending even though PayID itself supports real-time transfers. A pending request has not necessarily reached the payment phase. Until the operator releases it, the relevant clock is not the network’s transfer time. Once released, the receiving bank account and the payment route become relevant to completion. The practical question is therefore not only whether PayID is real time, but when the funds are actually sent.
There is also a legal boundary around the subject in Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games, including slots and table games, to people physically located in Australia is prohibited. Accordingly, descriptions of a casino withdrawal process are not an invitation or a service recommendation. The payment mechanics can be distinguished without presenting an offshore real-money casino as a lawful option for Australian residents.
For any statement about instant PayID timing, the defensible reading is precise: the transfer can move in real time after release, while the full interval from request to receipt includes whatever happens before release. Treating those as one clock turns a payment-system feature into a broader claim that the feature does not establish.
A claim of an instant PayID withdrawal is useful only when its clock is defined. The relevant interval may start when a withdrawal is requested, when the operator approves it, or when the funds are released to the payment network. Those are different events. A short payment-phase time does not establish that the full request-to-receipt process is equally short.
A specialist review reported average PayID payout times of 30–90 seconds for the options it assessed. That figure describes a reported average, not a guaranteed result for every transaction. Without a clear definition of the start and end points, even a precise-looking time cannot show whether the measurement covers operator handling as well as the transfer itself.
The opposite case matters too. A specialist review found sites that advertised “instant” withdrawals but could take up to 24 hours because of internal review. The gap is not a contradiction in PayID’s transfer capability: it reflects a delay before funds are released. The advertised label can therefore describe the payment method while leaving the waiting period that matters to the account holder out of view.
A substantiated speed claim should make its scope plain. It should identify whether the quoted time begins at submission or release, and whether it ends at approval, dispatch or receipt. It should also state whether the figure is an average or a maximum. An average can be pulled down by quick cases while slower cases remain part of the same service; it is not a promise that an individual withdrawal will match it.
The evidence should be tied to the process being described. A measured transfer interval supports a claim about the PayID payment phase. It does not, by itself, establish how quickly a site reviews requests or releases funds. Conversely, a report of a long internal wait does not show that the payment network took that long after release. Keeping those stages separate prevents a fast network transfer from being presented as proof of a fast overall payout.
For comparisons, consistency matters more than a single striking time. The same start and end points must be used across the reported cases, and the average should not be presented as though it were a fixed service standard. If the claim gives no way to tell which stage was timed, the figure is incomplete evidence. “Instant” is a description, not a measurement; the useful detail is what happened between request, release and receipt.
In Australia, real-money online casino games are prohibited services under the Interactive Gambling Act 2001. The payment comparison below describes how the routes differ; it is not an endorsement of offshore casino services or a claim that such services are legally available to Australian residents.
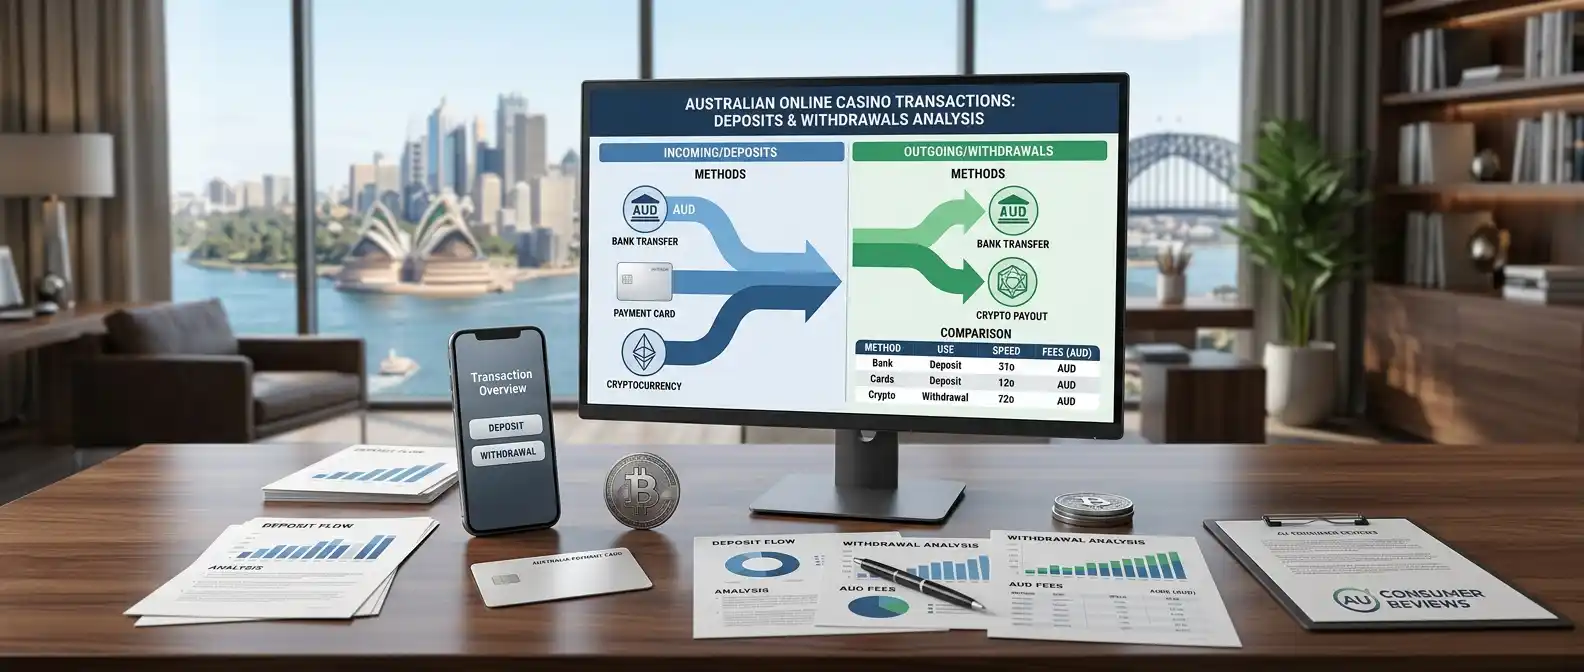
Once a payment has been released, PayID and a conventional bank transfer do not move at the same pace. PayID uses Australia’s New Payments Platform to transfer funds between bank accounts in real time. A report by filmink.com.au contrasts PayID’s near-instant transfer with bank transfers that may take several working days. That difference concerns the payment leg, not the time taken for a casino to approve a request.
Traditional bank transfers are the slower comparison point. A specialist review has reported that completion can take as long as five business days. That is a reported upper timeframe, not a guaranteed duration for every transfer. The route can therefore leave a noticeable gap between the moment funds are released and the point at which they appear in the receiving account.
Funds move in real time between bank accounts via the New Payments Platform once released.
Traditional routes that may take several working days, with some reports citing up to five business days.
Withdrawals are often processed within a day, sitting between real-time transfers and traditional bank routes.
Card payments also sit outside PayID’s real-time bank-to-bank mechanism. The precise timing depends on the payment route and processing arrangements; a card withdrawal should not be assumed to arrive at the moment it is approved.
E-wallets provide a separate alternative. Their withdrawals are described as being processed within a day, which is faster than a route that may take several days but not equivalent to PayID’s real-time transfer phase. “Processed” also needs careful reading: it can describe the operator’s handling of a withdrawal, rather than the moment the balance becomes available in the wallet. The wording of the stated timeframe matters as much as the method’s name.
The practical comparison is therefore about where elapsed time sits. PayID can move released funds rapidly between participating bank accounts. A standard bank transfer or card payment may add days at the payment stage, while an e-wallet may fall between those routes in the cited timing. None of these distinctions establishes how quickly a casino handles a request before releasing it.
For any payment route, the stated cashout time should be read as a sequence rather than a single promise: operator handling first, payment transmission after release, then receipt through the chosen method. PayID’s advantage concerns that final transfer leg. It does not turn a request into an immediate receipt, and a slower bank or card route does not by itself explain how long the operator takes before payment begins.
A PayID transfer can move through Australia’s New Payments Platform in real time, but that speed begins only after the operator has approved and released the funds. Before release, a withdrawal request remains inside the operator’s own process. The payment network cannot shorten a queue it has not yet received.
That distinction changes how an “instant withdrawal” claim should be read. It may describe the transfer after release, while saying little about the time between submitting a request and the operator authorising it. The request can be awaiting review even when the payment method itself supports near-instant movement. In accounting terms, the clock has separate stages: authorisation first, transfer second.
Operator processing can involve a queue, a review of the transaction, or a decision to hold the request for further checks. The specific process varies by operator. A submitted request is therefore not the same event as a released payment, and a status such as “pending” does not mean that PayID has started moving the funds. Only after the operator sends the payment onward does the network’s transfer speed become relevant.
A specialist review reported that some sites promoted instant withdrawals while retaining requests for internal review for as long as 24 hours. That is a report about those sites, not a universal timetable. It does show why the advertised label alone is insufficient: the slower part may sit entirely before the transfer begins.
The practical measure is the full interval from request submission to receipt, with the operator’s approval stage shown separately from the payment stage. If a published processing estimate covers only the transfer after release, it should not be treated as a promise about the entire withdrawal. Conversely, a delayed approval does not establish that PayID itself is slow.
For a real-money casino transaction, the operator’s stated process matters because it controls when funds are released. The relevant terms are whether requests are reviewed before release, how the operator communicates a hold, and what event marks approval as complete. Without those distinctions, “instant” can describe a narrow segment while leaving the total elapsed time unclear.
In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. That legal position is separate from the technical function of PayID: a payment network’s capacity for real-time transfers does not make a prohibited gambling service lawful. Payment speed and operator approval are different questions, and neither changes the other.
A first cashout can involve an identity check before any payment is released. In a specialist review of casino payout procedures, first withdrawals are identified as a point at which verification may be requested. This is an operator-side control: PayID’s ability to move a payment in real time does not remove the need to establish who owns the account requesting it.
Know Your Customer checks, usually shortened to KYC, are the identity-verification procedures used to connect an account with the person using it. Casinos must verify a player’s identity before processing a withdrawal. Until that check is complete, a request may remain pending even if the selected payment method supports rapid transfers. The payment network cannot compensate for an account that has not cleared the operator’s verification process.
Timing matters because verification requested only after a withdrawal is submitted adds a separate step to the process. The operator may need to request information, assess it and confirm the account before continuing. That creates an interruption before payment release, rather than a delay caused by PayID itself. A displayed status such as “pending” therefore does not, by itself, indicate a problem with the payment rail.
Completing identity verification in advance can significantly speed up later withdrawals. It shifts the check away from the point when funds are being requested, reducing the chance that a first cashout will pause while the account is assessed. It does not guarantee immediate processing: a completed check does not remove other operator-side conditions, and it does not change the time taken by a payment route once funds are released.
A useful distinction is between verification status and withdrawal status. An account may be registered but not yet verified for cashouts; those are not equivalent states. Where a service provides an account-verification area, its displayed status is more informative than the mere ability to log in or make a deposit. Any request for additional information should be treated as an unresolved condition on processing, not as evidence that the payment has already been sent.
For a PayID cashout, the sequence is therefore conditional: identity verification must be completed, the operator must be able to process the request, and only then can the payment phase begin. Calling the whole sequence an “instant withdrawal” obscures the part most likely to hold up a first request. The term can describe the transfer after release; it cannot make an unfinished identity check disappear.
A PayID transfer can move quickly once released, but the amount requested may determine whether a withdrawal is released automatically or paused for review. The casino’s per-transaction maximum is only one part of the calculation: a separate cashout cap can restrict the total paid over a week or month. These are operator-set conditions, not limits imposed by PayID itself.
A specialist review reports that some top-tier Australian PayID casinos automatically approve withdrawals below AUD 5,000. That threshold is a reported operator practice, not a market-wide rule. An amount below it does not guarantee automatic release: other account or transaction conditions may still prompt a check. A request at or above the stated threshold may also need manual assessment, depending on the operator’s policy.
The amount can affect the timing even when a request fits within the transaction maximum. A specialist review identifies withdrawals above AUD 2,000 among situations that can face additional delay. This is a reported review trigger, not proof that every operator uses that amount as a fixed cutoff. The practical distinction is between an amount the system can accept and one the operator is willing to release without further scrutiny.
Limits also need to be read together. A casino may set a maximum for one transaction and a separate weekly or monthly payout ceiling, according to a specialist review. Meeting the per-transaction limit therefore does not establish that the full balance can be withdrawn within the same period. If the requested amount exceeds a relevant cap, the payout may need to be divided or deferred under the operator’s rules. Large withdrawals may also be released in instalments where the operator’s policy provides for that.
Withdrawal amounts can be restricted by casino policy, as reported by filmink.com.au. The policy determines the payable amount and may shape the release schedule; PayID cannot override it. That is why an advertised instant payment method does not settle the question of when the full balance will arrive.
A useful comparison is the requested amount against three separate figures in the withdrawal terms: the per-transaction maximum, any weekly or monthly cap, and the amount that qualifies for automatic approval. If the terms disclose a manual review threshold, that condition should be considered separately from the payment method’s transfer speed. Where a limit forces a request into multiple payments, each release remains subject to the operator’s process. The arithmetic is simple; the conditions are where the timetable changes.
Payment routing is a separate condition from the transfer network’s speed. A PayID transfer may move in real time after release, but that does not resolve a mismatch between the payment details used to deposit and those entered for a cashout. Operators generally return funds to the original deposit method where possible. For PayID, the identifier used for the withdrawal should therefore match the one used for the deposit, and the destination account must be linked to the casino profile.
This is not merely a formatting preference. Using different PayID details can trigger a security review, interrupting the route before funds are released. The practical check is to compare the PayID recorded on the deposit transaction with the identifier entered for the withdrawal. A different email address or mobile number may point to a different PayID, even if both identifiers belong to the same person. Where details have changed, the account record and payment route need to be consistent before a withdrawal request is submitted.
Payment-method rules can also affect the available route. If a deposit method can accept returned funds, the operator may require the withdrawal to go back through it rather than allowing a switch to PayID. Where return to the original method is not possible, the operator’s stated process determines which alternative is accepted. The PayID option shown in a cashier does not, by itself, establish that every balance can be routed through it.
A standard request may involve opening the Wallet or Withdrawal area, entering the PayID identifier, specifying the amount and confirming the transaction. The details matter at each step: the destination should belong to the account holder and be linked to the casino profile. A typo or an identifier associated with another account can leave the payment route inconsistent with the deposit record. The resulting issue is administrative, not a delay in PayID’s bank-to-bank transfer mechanism.
Fees require a separate check. A report by filmink.com.au notes that a transaction fee may apply when PayID is used for a withdrawal. That is a possibility, not a fixed charge applicable to every transaction. The fee schedule should be checked before confirming the request, because a deduction changes the net amount received even when the payment route works as intended.
For a meaningful comparison, the amount requested and the amount expected in the receiving account should be treated separately. The first is the withdrawal instruction; the second may reflect any applicable fee. If the operator’s terms do not make the fee clear, the payout figure cannot be calculated reliably from the requested amount alone. Matching deposit and withdrawal details reduces avoidable routing friction; it does not remove operator processing conditions or establish that the full request-to-receipt process is instant.
Payment options described for offshore real-money casino services are not interchangeable: some are designed to move funds between accounts, while others are deposit-only. That distinction matters before comparing speed. Real-money online casino games are prohibited for operators to provide to people in Australia, so payment descriptions should not be read as an endorsement or an assurance that a service is lawful.
Payment-method guides covering the market list bank transfers, debit cards, PayPal and Skrill, with cryptocurrency also appearing at some operators. Credit cards must not be accepted for online gambling services. Each route has separate conditions, and the payment label alone does not establish whether deposits and withdrawals are both supported.
E-wallets such as PayPal and Skrill hold funds in a separate account before they are sent onward. A specialist review describes e-wallet transactions as being completed within hours rather than days; that is a report about the services it assessed, not a fixed timetable across operators. E-wallets can therefore differ from a direct bank route in how the money is held and routed, even when the same account holder is involved.
Bank transfers are standard but slower, while instant banking (e.g., POLi) connects accounts via a provider. Cryptocurrency can be near-instant but uses a different system, and prepaid vouchers like Neosurf are typically limited to deposits only.
Bank transfers move funds between bank accounts. They are a familiar route, but the time taken depends on the service and its processing conditions. That makes them distinct from instant banking, which connects a payment to a bank account through a provider. A specialist review reports that some real-money casino services aimed at Australians have offered instant banking through providers such as POLi. Availability is operator-specific, and the label does not mean every stage of a transaction is immediate.
Cryptocurrency is another option described in some payment guides. A specialist review reports that crypto transactions can be near-instant, but that does not make the method equivalent to a bank transfer: it uses a different payment system and may not be accepted for both deposits and withdrawals. The operator’s stated conditions determine which transaction types are supported.
Prepaid vouchers work differently again. A specialist review reports that cards and vouchers such as Neosurf are generally available for deposits, but not withdrawals. They can add funds without providing a matching route for cashing out; another method may be required to receive money.
The practical comparison is therefore not just a list of brand names. It is whether a method supports deposits, withdrawals, or both; whether funds pass through an intermediary account; and what processing conditions apply. Any advertised payment choice should be checked against its stated use and terms, rather than assumed to work in both directions.
A payment method can move funds quickly only after a withdrawal is eligible to proceed. Bonus wagering sits earlier in that sequence: if the applicable conditions remain unmet, the balance may not be available for cashout, regardless of whether PayID is selected. “Instant withdrawal” therefore says nothing about whether bonus-related restrictions have been cleared.
A specialist review describes two ways wagering requirements may be calculated. One applies them to bonus funds alone; the other calculates them against the combined deposit and bonus. The distinction changes the amount of activity required before the funds become withdrawable. Bonus-funds-only wagering is preferable because the deposit is not added to the calculation. A headline offer does not show which basis applies.
The calculation also affects the status of the balance. A displayed total can include funds that are not yet eligible for withdrawal under the offer’s conditions. Until wagering is complete, a cashout request may be blocked or the bonus may be subject to the offer’s stated rules. The payment stage has not failed; the request has not cleared its preceding condition.
This matters when assessing a claimed instant PayID withdrawal. A fast transfer cannot compensate for an unfinished wagering requirement, and a payment-speed claim should not be read as a promise that every balance can be withdrawn immediately. The relevant question is whether the amount being requested is available under the bonus terms, not merely whether PayID is offered as a payment route.
The calculation should be checked before accepting an offer. The terms need to identify whether wagering applies to the bonus alone or to the deposit and bonus together, and what happens to each part of the balance if the conditions are not met. If the basis is unclear, the apparent value of the offer cannot be assessed reliably. A larger combined calculation can make the withdrawal condition materially harder to satisfy, even where the payment itself is quick.
These conditions are not a minor footnote to a cashout. They determine whether the withdrawal can begin at all. An advertised payment speed measures only one part of the process; bonus eligibility is a separate gate, with its own calculation and rules.
In Australia, the legal distinction is material: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in the country. Discussion of wagering terms does not make such an offer lawful or recommend using it. Where offshore offer conditions are being assessed, the bonus calculation should be treated separately from the speed of any payment method.
A stated payout time is meaningful only when the terms define what the clock measures. “Instant” may refer to the transfer after release, not the period between submitting a withdrawal request and receiving funds. PayID moves money between bank accounts in real time through Australia’s New Payments Platform (NPP), but that network timing does not establish how long an operator takes to process a request.
The legal context is material: under the Interactive Gambling Act 2001, operators must not provide real-money online casino games, including pokies, to people physically located in Australia. The details below describe how withdrawal terms are structured; they are not an endorsement or recommendation to use such a service.
A specialist review reports that reputable PayID casinos publish minimum and maximum withdrawal limits clearly. Those figures define whether a requested amount can be paid through the stated method and whether a balance may need to be divided or handled another way under the operator’s rules. The minimum matters when a small balance remains; the maximum matters when a requested cashout exceeds the permitted amount.
The terms should make clear whether limits apply to each transaction or to withdrawals over a stated period. They should also explain what happens when a request falls outside a limit. A maximum shown without its scope is incomplete: a per-request ceiling and a broader cashout cap are different conditions, even if both are labelled “maximum withdrawal.”
A fee can reduce the amount that reaches the linked account. A report by filmink.com.au notes that a PayID transaction fee may apply, so the relevant terms should state whether a charge is taken from the requested amount, added separately, or dependent on a condition. If the fee is not specified clearly, the final amount cannot be calculated from the advertised withdrawal figure alone.
The calculation is straightforward once the wording is clear: requested amount less any stated deduction equals the expected transfer. A fee described only in general terms leaves that result unresolved. The terms should also identify whether the fee is charged by the operator or associated with the payment route.
Processing conditions determine when the payment phase begins. The terms should distinguish the operator’s handling of a request from the transfer itself, and state the applicable processing window and any conditions that can pause it. A claim of an instant PayID transfer is not a promise that a withdrawal request will be completed instantly from submission to receipt.
For an instant withdrawal on a pokies service, the useful reading is therefore literal: locate the minimum, maximum, fee wording and processing conditions, then identify which stage the stated time covers. PayID’s real-time network capability describes the movement of funds after release. It does not replace the operator’s published conditions or convert an undefined processing period into a defined one.
PayID transfers can arrive in real time once the operator releases the funds; reported averages for some options were 30–90 seconds. The full wait can be longer because of operator reviews, first-time identity checks, larger withdrawals or bank processing windows, and some advertised instant withdrawals have taken up to 24 hours.
Options mentioned include credit and debit cards, PayPal and Skrill, bank transfers, PayID and, at some sites, cryptocurrency. E-wallets are often processed within hours, while bank transfers can take up to five business days; prepaid vouchers such as Neosurf are generally for deposits, not withdrawals.
The term usually refers to casinos with straightforward cash-out processes, clear limits and fast payment after a withdrawal is approved and released. However, providing real-money online casino games to people in Australia is prohibited under the Interactive Gambling Act 2001.
Compare when the stated payout clock starts and ends, whether a speed figure is an average or guarantee, and the site’s published limits, fees and verification requirements. In Australia, real-money online casino games for people located in the country are prohibited under the Interactive Gambling Act 2001.
Published by the Norco Casino team.